Currently there are bloated inventories for Bauelemente like memory, small case-size ceramic Kondensatoren and automotive MCUs, but FPGAs, analogue ICs, power MOSFETs, MCUs and discretes remain constrained and costly.
In Q3, Lieferzeiten for all elektronische Bauelemente will reduce compared to Q3 2022 with nearly 60% of component Lieferzeiten decreasing versus 1% in Q3 22 with none expected to increase compared to 73% in Q3 22.
Despite inventory reductions that will likely be complete by the end of H1, IC orders, wafer starts, and capacity utilisation will begin to rise and memory pricing will reach its bottom in H2. DRAM prices will start to recover in Q3 and NAND pricing will follow in Q4 or early in 2024.


Abonnieren für regelmäßige Marktupdates. Bleiben Sie auf dem neuesten Stand der Branchentrends, indem Sie unseren Newsletter abonnieren. Unser Newsletter ist Ihr Zugang zu erstklassiger Marktexpertise.
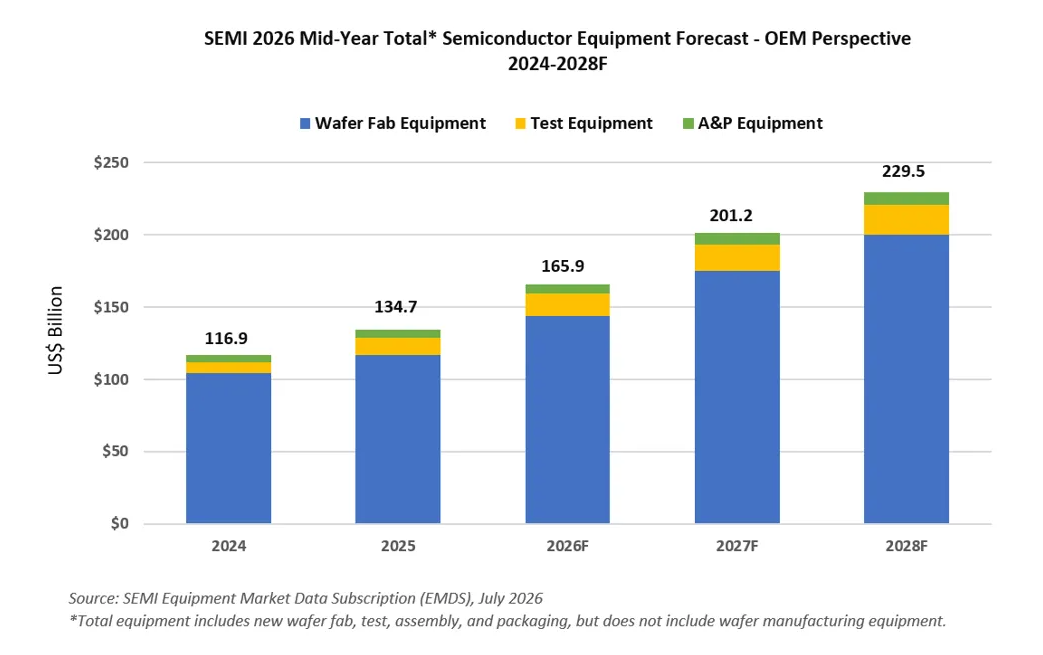
Following a record-setting year for the Halbleiterindustrie, the start of the new year has continued the momentum, as semiconductor Umsatz grew 27% in 1Q26 from 4Q25 to reach US$319bn, according t


